Wednesday, May 16, 2012

It Pays to Have a Good Memory


It Pays to Have a Good Memory

In today’s housing market, it can pay (quite literally) to have a good memory. That’s because a good memory can help you stand out from the competition — especially when you’re networking and trying to remember names.

Unfortunately, many of us have trouble remembering the name of someone two minutes after we shake her hand. If that sounds like you, don’t worry… you’re not alone. It's actually an extremely common occurrence for many people. The good news is there are a number of simple, practical steps you can take to improve your memory now and long into the future. Here are just two of the great tips for proactively strengthening your memory.

Tip #1: Neurobic Exercise

You know all about the wonderful effects aerobic exercise has on the heart, but have you heard of neurobic exercise for the brain?

According to Lawrence Katz, co-author of Keep Your Brain Alive: 83 Neurobic Exercises, the best exercise for the brain is to force it to form "new patterns of association" or new pathways. In other words, challenge your brain every day. Take it off autopilot and make it relearn or create new associations with the most routine activities of your day.

Katz's book offers numerous examples of small changes you can make to activate your brain, including: brushing your teeth with the other hand; taking an alternative route to work; moving your wastebasket to the other side of your desk; closing your eyes while putting your key in and unlocking the front door; and changing where you and your family members sit at the dinner table.

So if you feel like your memory might be starting to slip a bit, try some of these simple neurobic exercises today!

Tip #2: Mnemonic Drilling

There are actually three steps or stages of memorization: acquisition, consolidation, and retrieval. That means, once we acquire new information, like someone's name for instance, the way in which we consolidate that data will directly affect how well we're able to retrieve it from memory.

Whether you're a visual or auditory type of learner, there are many mnemonic devices that can help you to better organize or consolidate the new information that you need to recall.

Here's an example of simple steps that might help:

First, associate the data you want to remember with common images. For instance, let's say you meet someone named Jennifer Green. Imagine Jennifer playing golf, or picture her wearing all green clothes, or imagine her face painted completely green.

Second, think of associations you can use to help you remember this person. For instance, link Jennifer to the quality that best fits her personality (use alliteration and rhymes whenever possible): Jolly Jennifer Green.

Finally, connect sound to your memory by saying the name aloud.

Do this regularly and, before you know it, you'll never forget anyone's name again! And that can give you a nice advantage in networking and communicating with clients! 

Monday, May 14, 2012

Mortgage Market Guide Vol. 10 Issue 20

Last Week in Review: Bonds and home loan rates improved to record levels — find out why.

Survey says? Last week’s economic report calendar may have been light, but some important surveys revealed key data to note. Read on for the details...and how home loan rates fared.

As you can see in the chart, the National Association of Realtors (NAR) said that of the 146 Metro cities surveyed, home prices rose in 74 of them in Q1 2012. This is up from 29 cities that saw an increase in home prices in Q4 2011. In addition, the NAR also said that inventories for existing homes fell 22% since this time last year and are down 41% since the peak in mid-2007. While the housing market has a long way to go, this report was a nice step in the right direction.

There was also news from the National Federation of Independent Business, which said that its small business optimism index gained 2% in April as the survey revealed that companies have increased plans for hiring and investing in the future. While companies added new employees at a slower pace in April than in March, the index rose to 94.5 — the highest level since February of 2011. Overall, though, the report showed that our economy is improving but is still fragile. The state of our economy is part of the reason for the improvement in Bonds (and home loan rates, which are tied to Mortgage Bonds) of late.

Another big reason that Bonds and home loan rates have been improving is the fresh round of uncertainty out of Europe. France elected a new president, and this change of the guard represents the ninth EuroZone leader swap since the financial crisis began. Greece is also back in the news and their citizens are not taking to the austerity measures either. The New Democracy government, a pro-bailout party, is having trouble gathering the support to rule the government. This has sparked some safe haven trading into our Bonds, as investors see our Bonds as a safe place for their money.

The bottom line is that now continues to be a great time to purchase or refinance a home, as home loan rates remain near historic lows. Let me know if I can answer any questions at all for you or your clients.

Forecast for the Week: A full slate of economic reports is ahead, with news on inflation, the housing market, manufacturing and more.

As you can see in the chart below, Bonds and home loan rates reached record best levels last week. I’ll be monitoring the markets closely this week to see what happens next.

Chart: Fannie Mae 3.5% Mortgage Bond (Friday May 11, 2012)


With earnings season behind us, investors will be deluged with a slew of economic reports that will touch on many segments of the U.S. economy: 
  • Retail Sales will be released on Tuesday. This report gives the markets some insight to how consumer spending is holding up.
  • Also on Tuesday, the Consumer Price Index (CPI) will report on inflation at the consumer level. Last week’s Producer Price Index showed that inflation at the wholesale level has moderated, thanks to lower energy prices. Will CPI follow suit?
  • Manufacturing from the New York Empire and Philadelphia Fed Index will also be released Tuesday and Thursday, respectively.
  • Housing Starts and Building Permits data will be delivered on Wednesday.
  • Last — but not least — will be the Weekly Initial Jobless Claims numbers on Thursday. Last week's data was the lowest in a month.
In addition to those reports, European headlines will continue to dominate the news as the debt woes in that region plague the global economies. Also, the minutes from the Fed's April meeting of the Federal Open Market Committee will be released and this could move the markets. 

Remember: Weak economic news normally causes money to flow out of Stocks and into Bonds, helping Bonds and home loan rates improve, while strong economic news normally has the opposite result. The chart above shows Mortgage Backed Securities (MBS), which are the type of Bond that home loan rates are based on.


When you see these Bond prices moving higher, it means home loan rates are improving — and when they are moving lower, home loan rates are getting worse.


To go one step further — a red “candle” means that MBS worsened during the day, while a green “candle” means MBS improved during the day. Depending on how dramatic the changes were on any given day, this can cause rate changes throughout the day, as well as on the rate sheets we start with each morning. 


View: Did you know that bad news can be good for home loan rates? Be sure to read the article below.

Why Bad News Can Be Good for Home Loan Rates


It may seem odd that negative economic news can actually be good for home loan rates, but there's a pretty simple explanation for this phenomenon. Here’s a concise explanation you can share with your clients or you can use to gain a better understanding yourself.


First, we need to remember that big money managers who are in search of higher returns avoid holding onto cash by investing in both Stocks and Bonds.


Second, we need to dispel the myth about how home loan rates are determined. Despite what it may sound like in news stories covering the Federal Reserve’s meeting, home loan rates are based on the performance of mortgage-backed securities — which are a type of Bond.


When we put those two points together, we see that whenever the economy is on fire and there are good economic news reports, investors tend to put more money into Stocks. That’s because Stocks offer higher returns, even though they are generally more risky. To put money into Stocks, however, investors must remove some of their money from less-risky Bonds. The result is a decreased demand in Bonds that causes Bond prices to worsen, which causes home loan rates to go higher.


Inversely, when the economy is sluggish and economic reports are negative, money managers tend to take money out of higher-risk Stocks to put it into less-risky Bonds. As demand for Bonds increase, Bond pricing improves and home loan rates go down.


So while it may seem odd that home loan rates improve when economic news is sluggish, it actually makes sense when you look at the big picture.


If you have any questions about how the economic news is impacting home loan rates, please just call or email. I’m always happy to chat about what’s happening in the markets and what it means to home loan rates. 
 

Tuesday, May 8, 2012

Mortgage Market Guide Vol. 10 Issue 19

Last Week in Review: The Jobs Report for April is in, but what did the news reveal about our economy?

Take this job and love it. And the Labor Department’s Jobs Report for April showed that fewer than expected people are able to do this, as fewer than expected jobs were created. Read on for details and what they mean for home loan rates.

The Jobs Report showed that 115,000 jobs were created in April, with 130,000 private sector jobs offsetting government job losses. This number was a disappointment and below expectations. The only silver lining in the report were upward revisions to the previous month's readings which added 53,000 more jobs than what was previously reported.

The unemployment rate dropped a tick to 8.1% — the lowest since January 2009. However, the decline was mainly due to the labor force shrinking by 300,000, rather than by robust job growth. And as expected, we are starting to hear more and more about the Labor Force Participation Rate (LFPR). The LFPR dropped to 63.6, the lowest ratio since December 1981. Why is this important? The LFPR gives us a clear read of who is working and who is not.  And if someone is not participating, then they are probably receiving some sort of social security or unemployment insurance. The bottom line is that it is tough to pay down debt when there are not enough people participating in the labor force. 

Overall the Jobs Report was underwhelming and, unfortunately, further accommodative monetary policy or even more Bond buying (known as Quantitative Easing or QE3) will have a very limited effect on job growth. What’s more, the debt drama in Europe continues to escalate, as both Italy and Germany reported higher than expected unemployment rates, while Spain has slipped into its second recession since the financial crisis.

The events in Europe and potential softening of our economy have resulted in home loan rates remaining near historic lows. That means now continues to be a great time to purchase or refinance a home. Let me know if I can answer any questions at all for you or your clients. 

Forecast for the Week: A quiet week is ahead, but an important inflation report will be released.

 As you can see in the chart below, Bonds and home loan rates reached record best levels after last week’s Jobs Report. I’ll be monitoring the markets closely this week to see what happens next.

Chart: Fannie Mae 3.5% Mortgage Bond (Friday May 04, 2012)


After two weeks featuring a slew of economic reports, this week's calendar is light. But that doesn’t mean there won’t be a battle for investing dollars in the Stock and Bond markets!
  • The first report won't be released until Thursday with the weekly Initial Jobless Claims report. Last week, claims fell by 27,000, which was the largest weekly decline since May 2011.  
  • On Friday, inflation at the wholesale level will be released in the form of the Producer Price Index (PPI). Last week it was reported that the year-over-year Core Personal Consumption Expenditures (PCE) rose to 2%, the high end of the Fed's range.
  • The last report on Friday will be the first reading on Consumer Sentiment for May.
With so few economic reports this week, market players will be focusing in on the ongoing debt crisis in Europe, earnings reports and how the $66 Billion in Treasury Notes and Bonds will be received. All three of those news items could move Bonds and home loan rates this week.


Remember: Weak economic news normally causes money to flow out of Stocks and into Bonds, helping Bonds and home loan rates improve, while strong economic news normally has the opposite result. The chart above shows Mortgage Backed Securities (MBS), which are the type of Bond that home loan rates are based on. 


When you see these Bond prices moving higher, it means home loan rates are improving — and when they are moving lower, home loan rates are getting worse.
To go one step further — a red “candle” means that MBS worsened during the day, while a green “candle” means MBS improved during the day. Depending on how dramatic the changes were on any given day, this can cause rate changes throughout the day, as well as on the rate sheets we start with each morning. 


Wednesday, May 2, 2012

Cinco de Mayo: The Story You May Not Know


Cinco de Mayo: The Story You May Not Know

In a few days, we’ll mark the celebration known as Cinco de Mayo. Although many people have heard of this celebration, most people don’t realize that the event being commemorated may have actually played an important role in shaping the United States that we know today.

Feel free to share the interesting facts below with clients and friends in the coming days! You may surprise them with what you’re about to read.

What Does Cinco de Mayo Commemorate?

Many people believe that Cinco de Mayo is the day that recognizes Mexico's independence from Spain. To set the record straight, that conquest happened on September 15th, 1810. Cinco de Mayo, on the other hand, celebrates an event that took place over 50 years later.

On May 5, 1862, the Mexican cavalry, under the command of Texas-born General Zaragosa, defeated the French at the battle at Puebla, a city 100 miles east of Mexico City.

The French army, having not suffered a defeat in nearly 50 years, landed in the port of Vera Cruz and headed toward the capital city with a specific mission. Fearless of any opponent, the French sought to overthrow the capitol and gain control of Mexico, even bringing along a Hapsburg prince to oversee the would-be empire.

Cinco de Mayo’s Connection to the United States

The goal of France's leader, Emperor Napoleon III, was to gain proximity to the US in hopes of supplying the Confederate Army in their fight against the North. He had a vested interest in sustaining the division within America.

To America's benefit, the undersized Mexican cavalry used their knowledge of the terrain to defeat the powerful French army. This victory enabled the northern states to build the greatest army in the world at that time.

Fourteen months later, the North soundly defeated the Confederate Army in the battle at Gettysburg, thus ending the civil war. Union troops were subsequently rushed to the Texas/Mexican border to help expel the French from Mexico.

For this reason, Cinco de Mayo is celebrated in both countries. More importantly, it's a great occasion to honor freedom and liberty.

Tuesday, May 1, 2012

Mortgage Market Guide Vol. 10 Issue 18

Last Week In Review: The Fed met, but was there mention of more Bond buying?

"I’m still standing – yeah, yeah, yeah." Elton John. And after last week’s Fed meeting, Bonds and home loan rates are still standing near record best levels. Read on for details.
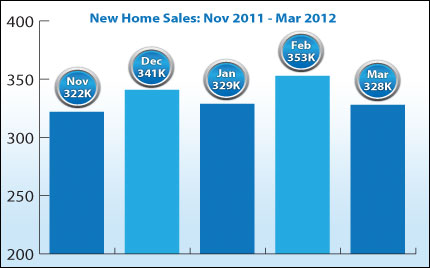
After last week’s regularly scheduled meeting of the Federal Open Market Committee (FOMC), Fed Chairman Ben Bernanke acknowledged that conditions in our economy are improving modestly, but he noted that the housing market remains depressed. One example of this is New Home Sales, which fell 7.1% in March to 328K units on an annual rate.


Bernanke also noted that inflation is higher in the short-run due to higher energy costs, but that the Fed expects prices to moderate and remain in check longer-term. Remember, inflation hurts the value of fixed investments like Bonds (including Mortgage Bonds, to which home loan rates are tied)...so inflation staying in check is crucial when it comes to home loan rates remaining near record best levels.


One important subject the Fed didn’t mention in their Policy Statement was another round of Bond buying to stimulate our economy (known as Quantitative Easing or QE3). This wasn’t much of a surprise because — after several moves to prop up the economy — the Fed must see where upcoming economic reports go before venturing to underwrite the economy further. If the housing market remains depressed and the economy doesn't pick up steam, QE3 could be a very real possibility.


And there was a bit of a sluggish read on our economy last Friday, after the Fed’s mid-week meeting. The advanced (first of three readings) of Gross Domestic Product (GDP) for the 1st Quarter of 2012 came in at 2.2%, well below expectations. This was also well below the 3% final 4th Quarter 2011 GDP reading. Within the report it showed that the personal consumption expenditure inflation reading rose at the fastest pace since the 2nd Quarter of 2011. This is definitely something the Fed is watching closely. 
As 2012 continues to unfold, inflation, the housing market, our sluggish economy, and our ever-growing debt are important issues that the Fed and our government need to address. Seeing the debt crisis in Europe escalate must put a sense of urgency on our government to reign in our annual budget deficit and overall debt. This mix of factors will continue to impact the direction in which Bonds and home loan rates move in the weeks ahead.


The good news is that now continues to be a great time to purchase or refinance a home, as home loan rates remain near historic lows. Let me know if I can answer any questions at all for you or your clients.


Forecast For The Week: A full slate of economic reports ahead, with news of inflation, manufacturing, and the job market.

As you can see in the chart below, Bonds and home loan rates continue to hover near record best levels. I’ll stay on top of this week’s news to monitor how Bonds and home loan rates are impacted.

Chart: Fannie Mae 3.5% Mortgage Bond (Friday Apr 27, 2012)


A slew of economic reports are set for release this week, and investors and traders will be watching the data closely for any signs of an economic slowdown:
  • Right off the bat on Monday the Personal Income and Spending data will be released along with the closely watched Core Personal Consumption Expenditure (PCE) report. The Core PCE is the Fed's favorite gauge of inflation and comes after Fed Chairman Ben Bernanke said last week that inflation in the short-term has been pressured higher by rising energy costs.      
  • In the manufacturing sector, the Chicago PMI will be released on Monday with the national ISM Index delivered on Tuesday. 
  • On Wednesday, the ADP Employment Report will be released ahead of the government's monthly Non-farm Payrolls and the Unemployment Rate on Friday.         
  • Initial Weekly Jobless Claims will be released on Thursday. The recent couple weeks of elevated Jobless Claims is disturbing…and if it continues, rest assured QE3 chatter will re-emerge.
Remember: Weak economic news normally causes money to flow out of Stocks and into Bonds, helping Bonds and home loan rates improve, while strong economic news normally has the opposite result. The chart above shows Mortgage Backed Securities (MBS), which are the type of Bond that home loan rates are based on. 


When you see these Bond prices moving higher, it means home loan rates are improving — and when they are moving lower, home loan rates are getting worse.


To go one step further — a red “candle” means that MBS worsened during the day, while a green “candle” means MBS improved during the day. Depending on how dramatic the changes were on any given day, this can cause rate changes throughout the day, as well as on the rate sheets we start with each morning.  

Monday, April 30, 2012

Fun Housing Facts


Fun Housing Facts

The United States Census Bureau recently released some fun facts related to housing across the country, based on data for 2010. Here are just a few highlights from the release that you may find interesting…and may want to pass on to others.

Heating Our Homes
  • 57 million = Number of houses heated by utility gas.
  • 2.2 million = Number of houses heated by wood.
  • 38,010 = Number of houses heated by solar energy.
From Home to Work
  • 25.3 minutes = Average time workers across the country spent getting from home to work.
  • 31.8 minutes = Longest commute time in the nation, which belonged to Maryland residents.
  • 16.1 minutes = Shortest commute time in the nation, which belonged to North Dakota residents.
Home Sweet Home
  • 2,392 square feet = Average size of a single-family house built in 2010. That number was down a little from 2,438 square feet in 2009.
  • 131.7 million = Number of housing units counted in the 2010 Census. Compare that to 37.2 million in the first housing census, which was conducted in 1940!
Bonus Fact!

The first housing census in 1940 featured 31 housing questions - including some we may find odd today, such as whether the house had a radio…toilets or an outhouse…electric lighting…and running water.

Conversely, the 2010 census only included two housing questions: (1) whether the home was owned or rented and (2) whether the respondent sometimes lived or stayed somewhere else. The number of housing questions in the census has dropped because we now ask a number of housing questions in the American Community Survey, which is sent to about 3 million households nationwide every year.

Over the years, housing has really changed. But regardless of the time or location, one thing remains the same…there's no place like home!

Monday, April 23, 2012

Mortgage Market Guide Vol. 10 Issue 17

Last Week In Review: There was a mix of good, bad, and downright ugly news. Find out how new home loans responded.


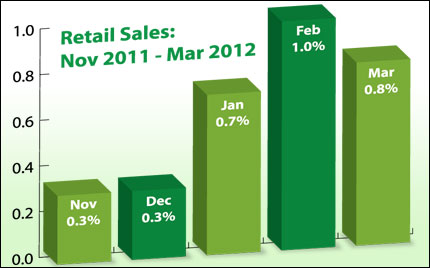
On the good side, Retail Sales in March rose by a nice 0.8%, as consumers bought all kinds of products across the board. And when stripping out autos, sales still grew. This adds to the increasing trend seen in January and February and is a good sign for our economy, as consumers don't spend when they aren't feeling optimistic about their financial situation.
"Bad news goes about in clogs, good news in stockinged feet." Welsh Proverb. And we certainly saw both good and bad news in the economic reports released last week. Here are the details...and what they mean for home loan rates.

But over in the manufacturing sector it was not as pretty a picture, as both the Empire State Manufacturing Index and the Philly Fed Index came in below expectations. This is largely being attributed to a global slowdown, and experts say that the outlook for our manufacturing remains positive…but just not accelerating at the present time. Things weren't as pretty in the housing sector either, as both Existing Home Sales and Housing Starts fell in March.

And things in the labor market were verging on ugly, as Initial Jobless Claims spiked sharply higher. The Labor Department reported 386,000 fresh Claims in the latest week, above the 375,000 that was expected...and well above the 350,000 range seen in recent weeks.

Also verging on ugly was news out of Europe. There is growing and very justified concern about Spain's ability to pay down debt, meet new budget deficit targets, and avoid a bailout or debt restructuring. The Spanish situation has prompted the G-20 (Finance Ministers and Central Bankers of the 20 largest economies) to urge the European Central Bank to do more to contain their debt crisis as it threatens global growth. And let's not forget that besides Spain, we still have France, Portugal, Ireland and Greece to deal with in future months and years.

So what does all of this mean for Bonds and home loan rates? There will likely be more safe haven trading into the relative safety of the US Dollar and US Bonds (which will benefit Mortgage Bonds, to which home loan rates are tied) as the uncertainty out of Europe escalates. And more bad economic reports here in the United States could add to this safe haven trading into our Bonds, just as more good economic news here would likely benefit Stocks at the expense of our Bonds and home loan rates.

This mix of factors will continue to impact the direction in which Bonds and home loan rates move in the weeks ahead. The takeaway is that home loan rates remain near historic lows and now continues to be a great time to purchase or refinance a home. Let me know if I can answer any questions at all for you or your clients.

Forecast For The Week: The Fed meets, plus there's news on consumer confidence, housing, the state of the economy and more.

As you can see in the chart below, the mix of news last week benefitted Bonds and home loan rates. I'll be watching closely to see what happens this week.
Chart: Fannie Mae 3.5% Mortgage Bond (Friday Apr 20, 2012)


The economic calendar this week will give the investor a broad view of the U.S. economy…but the Federal Open Market Committee (FOMC) meeting will be front and center in the minds of investors. Here's a break down of what to watch:

  • Consumer Confidence will be released on Tuesday…with Consumer Sentiment set to be delivered on Friday.
  • Also on Tuesday, New Home Sales for March will be released, followed by Pending Home Sales for March on Thursday.
  • On Wednesday, Durable Orders - which are products that are supposed to last at least three years - will be released.
  • Initial Weekly Jobless Claims will be released on Thursday. The number of new claims has been steadily rising in the past month, which is not a good sign for the labor markets. So all eyes will once again be on this report.
  • On Friday, the first reading on Gross Domestic Product (GDP) for the first quarter of 2012 will be announced.
Also on Friday, we'll see the Employment Cost Index, which measures the costs of hiring and paying the American workforce. Higher costs could lead to inflation pressures, which could push Bond prices lower and home loan rates higher.

In addition to those reports, this week's FOMC meeting will be closely watched by both the Bond and Stock markets for any clues on how the U.S. economy is holding up.

Remember: Weak economic news normally causes money to flow out of Stocks and into Bonds, helping Bonds and home loan rates improve, while strong economic news normally has the opposite result. The chart above shows Mortgage Backed Securities (MBS), which are the type of Bond that home loan rates are based on.

When you see these Bond prices moving higher, it means home loan rates are improving - and when they are moving lower, home loan rates are getting worse.

To go one step further - a red "candle" means that MBS worsened during the day, while a green "candle" means MBS improved during the day. Depending on how dramatic the changes were on any given day, this can cause rate changes throughout the day, as well as on the rate sheets we start with each morning.